Tuesday, July 29, 2008

Keep the Gears Engaged

engagedgears

It’s been much too long since I have posted here. I’ve been hard at work getting Maine State CU’s new web site ready to launch by the end of July (which is rapidly approaching and causing me much anxiety). So I just wanted to share a bit of the stuff I’m trying to work into our site as it launches or as we continue to improve it.


First, let me say that a little variety can go a long way with a site. Your site doesn’t need to have tons of flash animation or graphics to catch people’s eye. Sometimes its as simple as having a set of header images that rotate each time the page is refreshed. Make people feel like every time they load a page they see something new.


Second, I think its very important that there is a tie between the online channel and the in branch experience. Even though more and more members are using online banking every day, there will always be a need for that personal interaction. I think being personal is one of the single most important (though cliché) things a credit union can do to increase a member’s relationship with the credit union.


Your tellers are the face of your branch, so why not the online channel as well. Use images of the people and places your members recognize and interact with on a daily basis. This puts a face to what is typically a cold and impersonal experience filled with stock photography (stock photos make me cringe).


Third, coordinate your marketing across as many channels as you possible can. Visually and in the copy, try and keep things together. A fractured marketing campaign can only lead to fractured response. By keeping things consistent through copy, color, imagery, and message, you portray (even if the member only notices subconsciously) a professional and consistent brand. Also, something as simple as color coding between website sections and print materials can go a long way in making it easier for members to spot the information they are looking for.


It’s all about keeping your brand consistent through coordinating your marketing materials (whether in print or electronic), keeping the electronic channel personal, and providing the information members want to see in a convenient, logical, and easy to navigate format.


If you want to get your credit union moving, all the marketing gears have to engage each other, otherwise you're getting way less traction than you need.

Wednesday, July 2, 2008

The Hitchhikers Guide to Marketing?

DontPanic_1024

I've been rereading "The Hitchhikers Guide to the Galaxy" recently. First off, love this book, it appeals to many of my sides. The geek side loves the weird, creative sci-fi and my intellectual side revels in all the satire sprinkled into the (very twisted) storyline.

At one point in the story, the main characters find themselves on a ship full of marketers, accountants, and other "middlemen". They had been told their planet was doomed and that the entire population was to get into 3 giant ships and colonize another planet. The great thinkers in one, the middle men in a second, and the people who did the actual work in a third. They gave the middlemen a "head start". Turns out they just wanted to get rid of the middlemen.

Once the ship lands on what later is revealed to be prehistoric earth (yeah I told you the plot was bazaar) they begin trying to establish a civilization. After 500+ committee meetings, nobody has so much as discovered fire. One of my favorite quotes, and perhaps this strikes me as so funny because I'm now in marketing, is when a marketer in the group says (regarding their failed attempts at discovering fire) " you know that before any new product can be developed it has to be properly researched. We’ve got to find out what people want from fire, how they relate to it, what sort of image it has for them."

This got me thinking. Is it possible that we, as marketers, get so caught up in analysis and research that we lose sight of what might be a simple, elegant, and easy solution?

I'm not saying that we should just wing it with every new idea and product. There is a reason for research, a good reason, but does that sometimes get in the way of true creativity or blind some of us to the simplest solutions?

Thursday, June 26, 2008

Offering Budget Assistance to Build Loyalty

The following post was written by Aubrey Knorr, a teller at Maine State Credit Union. She has been with the credit union for a year and a half and has been a great member of the MSCU team. Enjoy!

Finances are on everyone’s mind lately.

Stock Photos

Due to the rising prices in our economy, we all are trying to re-write our budgets to cut out all of the pointless and unnecessary spending. We are re-thinking what’s really important. Unfortunately, setting a budget and actually sticking to it are not strengths that a lot of people have.

As a credit union, it’s our job to help our members to the best of our ability. Most credit unions don’t have actual financial advisors to assist members with these matters; there is a way to help our members in this area using the employees that we already have.

Many employees already know how to analyze and manipulate numbers. This talent can be utilized by placing them into a position that would enable them to sit with members and plan out budgets that the member can stick to, based on the members own income and expenses.

In a world of rising gas, food, and energy costs, on top of loans, credit cards (about 15% of people have more than $10,000 in debt!), childcare, and working long hours, our members need our help. If we can help them to consolidate and cut back with a budget that they can stick to, they will learn to trust us with any of their financial needs.

It will help us to gain more members with more accounts, and a lot of loyal people who will always come to where they are best served. Every credit union and bank has loans to offer and accounts to use, but how many have people that actually sit down with the member and go over their financial assets and needs with them?

We need to start looking at the newest needs of our members, and that is coping with the ever-changing fluctuation of the economy.

Wednesday, June 18, 2008

Mmmmmm…Financial Education: Is there anything it can’t do?

The following post was written by a friend and fellow Maine State CU employee, Dan Emery. He is a teller here at the credit union and has really stepped up in an effort to bring financial literacy to the front of our minds through research and connections.

Operating a successful business is anything but simple. It doesn’t matter what type of business you’re in, there are worries and challenges at every level. These include supply and demand, profit and loss, service standards, product standards, employees and payroll, the budget, change and improvement and the risks associated with decision-making. Before a business makes a decision it has to take into account the advantages and disadvantages of that decision. The litmus test for a decision is ultimately the bottom line; is it going to make money or will we lose money?

Credit unions deal with these same issues but we have a unique situation. Our litmus test for decisions is very simple; “Is this good for our members or is this bad for our members?”

Sometimes, to do what is best for our members we have to spend money that we may not recover in a typical sense, but it will help us gain loyal, long term members. Other times an opportunity presents itself that is beneficial to both the membership and the bottom line. This opportunity is Financial Education.

Here are a few statistics on financial literacy in our country today*:

  • 15 million adults receive phone calls from collectors or are considering filing for bankruptcy.
  • Only 2 in 10 keep track of their spending – regardless of gender, age or income
  • Only 59% of young adults in Gen Y pay their bills on time
  • The majority of Americans do not have a sufficient emergency fund (3 to 6 months of income saved)
  • More than 76 million adults say they do not have retirement savings

These stats are only the tip of the iceberg. With a little research you will uncover MANY more shocking statistics like these. So what do we do about it?

We need to help these people take control of their finances! We need to teach them how to budget, spend responsibly, save, reduce debt and build assets. This should not be a one time class; this should be a multiple step process over an extended period of time. We need to create one on one relationships with our members. We should let them ask questions and then help guide them to determine their goals, wants and needs.

How will this benefit our members? Through this process we will build a bond with our members that will make them feel respected, empowered and comfortable and we will earn their trust on an entirely different level. They will gain an understanding of their finances that will give them control, hope and less stress. It is a great feeling to have control and an understanding of your finances.

So what does the credit union get in return? Most importantly we get happy members!

We will create a reputation that people find attractive and it will show we are truly worthy of their business. If we help one person take control of their finances they will tell others how well they’re doing and how it happened; our name will get mentioned and we will attract new, long term members.

Gaining new, financially educated members will result in new accounts, new loans, more loans paid on time, fewer overdrafts and bounced checks, higher balances and more frequent use of our services by more people.

Not only should we strive to educate our entire membership we should also strive to set ourselves apart service-wise. We should do our best to lower fees, raise rates and make our members feel like they’re a significant part of their credit union and not a customer.

A thorough financial education program is a solid, long term win-win situation for both the member and the credit union.

Dan Emery

Maine State CU

Friday, June 6, 2008

The CUSO Conundrum

In my last post regarding Denis Dollar’s forecast for credit unions in 2020 the comments I got were an eye opener as to what CUSO’s are and what they do (thanks to everybody who commented and helped me further my understanding of the industry).


As I’ve thought about how CUSO’s can benefit credit unions, and more importantly, their members, I’ve had a few thoughts as to the way I feel they should be handled.


Jeffery Pilcher wrote, “My guess is that Dennis Dollar thinks CUs will pursue these ‘additional revenue streams’ wherever they can be found.” I don’t disagree with him, but my support of this is dependant on how credit unions deal with this additional revenue. Jeffery also posed the question of whether credit unions will use CUSO’s “in lieu of traditional, organic growth.”


I certainly hope not. In fact, I see a great benefit in using CUSO’s as a way to increase a credit unions ability to grow organically. By bringing in additional revenue through CUSO business, a credit union should be able to put that extra cash into serving the members. If the CUSO isn’t directly benefiting the membership, that extra revenue could (and should in my opinion) be used to offer lower rates on loans, higher returns on deposits, and research to provide them with innovative products tailored to their needs; which could turn more eyes to your credit union than a generic ad or extra branch.


There is, in my opinion, a place for CUSO’s in the credit union movement. They might even be instrumental in moving forward. More CUSO’s means more extra revenue, which means more (and less expensive) services for members. If we can keep that in mind as CUSO’s are created it could blow the doors open for a lot of credit unions. However, if that extra revenue is misused (which is completely subjective here mind you) CUSO’s could become merely a way to chase a higher profit margin.


I still think it is a stretch to believe that CUSO’s will outnumber credit unions in the coming decade. As Anthony Demangone stated in the comments, “…there are already credit unions out there with more than 10 CUSOs.” However, for every credit union that has 10 CUSOs, how many have zero, or have a stake in a single collaborative CUSO?


I feel like it still comes down to a saturation of the business landscape for credit unions. If credit union mergers continue, it is inevitable that a credit union with existing CUSO’s will merge with a credit union that has redundant existing CUSO’s. In such a situation, I assume that one of the redundant CUSO’s would be eliminated, or they would be merged. Either way you are left with one CUSO from two. Add that to the fact that, as Robbie Wright points out, “Credit unions are limited in what type of activities CUSO's can operate. In fact Jeff Russell at The Members Group can speak specifically to the pains of getting the NCUA to allow certain types of activities.”


So, in conclusion, I see a very valid reason for CUSO’s in the credit union movement. I do, however, still disagree with the suggestion that CUSO’s will outnumber credit unions themselves. Unless NCUA starts allowing some off-the-wall CUSO’s and credit unions are brave enough to go there, there are only so many ventures credit unions can get into. With mergers combining some of the existing CUSO’s, this would lead to a higher ratio of CUSO’s to CU’s, but I don’t think that ratio would ever flip. It would take many mergers and the disappearance of the niche credit union for this to happen. In my opinion, if those niche credit unions disappear, we’ve lost sight of what credit unions are all about in the first place.

Wednesday, May 21, 2008

Credit Unions in 2020 (or Will We Have Flying Cars?)

I read this article on CUNA’s web site a couple of days ago detailing how Dennis Dollar (how cool is that name) thinks the credit union landscape will look in the year 2020 (thanks to Deb Trautman for passing the article along). Now, I’ve never been one to put much faith in forecasts that stretch for a period more than 5 days (even the weatherman can’t get THAT period of time right) because things never look like you think they will. Heck, we were supposed to have flying cars 8 years ago according to many “forecasters”.


Distrust of long term outlooks aside, some of the predictions don’t quite jive with me.


  • Credit union service organizations will exceed the number of credit unions;

My understanding of a CUSO (and please correct me if I’m wrong on this) is that they are cooperative organizations of credit unions designed to help them deal with regulatory issues and the like. They are like a credit union’s credit union. From Wikipedia:

A Credit Union Service Organization (CUSO) allows a credit union the ability to conduct business that they would otherwise be restricted from due to regulatory constraints. Most CUSOs are limited liability companies (LLC) which also provide a measure of protection to the credit union from the actions of their CUSO. CUSOs are usually wholly-owned subsidiaries of their corresponding credit union, and most if not all of the profits generated by a CUSO are returned to the credit union. CUSOs can also sell stock, usually to other credit unions, to help fund the creation and operation of the CUSO. In this situation, the profits are then converted to dividends and paid out to shareholders as specified by the CUSO's charter.

CUSO’s, like any other business, operate based on demand. I don’t see the demand for CUSO’s ever warranting more CUSO’s than actual credit unions. In fact; wouldn’t that be bad business?


  • Credit unions will face greater regulatory pressures, and this will drive mergers;

Credit Unions may face an increase in regulatory pressures in the coming years. Some of it can be avoided by staying true to the credit union mission, and beyond that, showing people that we stay true to that mission.


Beyond the fact that some of this regulatory pressure might be avoided, the first bullet point about CUSO’s seems to be contrary to this one. If CUSO’s are there to help groups of credit unions stay in compliance with regulations, and there are more CUSO’s than credit unions, shouldn’t all the bases be covered?


It would be a shame to see so many unique, small credit unions disappear due to being unable to stay within regulatory guidelines. There is much to be said for a small credit union, dedicated to staying small, and dedicated to its membership. A prime example is Mt. Lehman Credit Union. They have, with the guidance of their General Manager, Gene Blishen, positioned themselves perfectly to serve their members. They know what those members want, and offer it to them. Things like their TextUs product cater to the people they serve. It isn’t a giant marketing campaign, but a product that connects the credit union with its members in a way many CU’s struggle with. As Morriss Partee would put it, they are a microbrew of a credit union; unique and incredibly awesome.


  • Credit unions will market cooperatively nationwide

This is kind of a vague one. By “market cooperatively” does he mean a nationwide brand? If so, I think you already know my opinion. Credit Unions are a diverse animal. To brand something, it takes a common thread, product, or culture. By trying to put all credit unions under a single brand, it smothers so many cool, unique credit unions (like MT. Lehman) that have a brand that works for them and their field of membership.


Not only does it smother uniqueness, but branding credit unions under a single banner would be nearly impossible. There are so many different cultures, each credit union has it own way of doing things, and a brand requires a coherent culture throughout. When you walk into a Starbucks, you can pretty much tell what your experience will be. Credit unions are totally different. Walking into Boston Firefighters’ Credit Union is necessarily different than walking into Maine State Credit Union because the demographic served by each credit union requires a different approach.


In the first part of the article, Dollar is quoted stating that, “The megabanks will lead to a disconnect with local citizens.” If credit unions end up nationally branding/marketing how would we be able to connect with local citizens any better than a megabank? Our strength is in our diversity, not our size.


  • Shared branching will be a key credit union differentiator, with nearly all credit unions participating nationwide, thus reinforcing a national branding campaign.

I’m sorry, but shared branching is not a differentiator. Shared branching is a way for credit unions to compete with the nationwide banks, but that’s as far as it goes. With BoA having branches on every street corner, the fact that you can do business at many credit unions nationwide does not make us different, it makes us the same. It is something we certainly need to educate our members about more often, but to say it differentiates credit unions from banks is nearly outrageous.


My take on credit unions in 2020?

Credit Unions, in my opinion, will be the main provider of community banking. Not based on national branding, not based on shared branching, not based on mergers, but based on diversity. Our strength has always been, and will always be, our ability to listen to our members and provide them with the things they want. Credit Unions will collaborate, rather than merge, to deal with regulatory pressures. They will collaborate to form marketing efforts if it applies to a shared demographic. They will collaborate to pass innovative new products and services from one credit union to another, allowing each credit union to tailor the innovation to their members’ needs. What we need is not a national brand, but to work as a team of unique, individual credit unions. That is where the strength, differentiation, and innovation lie.

Wednesday, May 14, 2008

Save-or-Sink: Financial Literacy as a Brand Message

I’ll start this off by saying; I think credit unions have a huge opportunity coming up. Where many see a problem, we should see the opportunity to stay true to the credit union mission and to differentiate ourselves from banks.

What is this opportunity you might ask? Financial literacy of course!

According to The Young Americans Center For Financial Education:

  • Of the 6000 students that took the Jump$tart survey, 62% of them failed.
  • In the 18-24 age bracket 30% of their average monthly income goes to debt repayment.
  • 45% of teen know how to use a credit card while only 26% showed understanding of interest rates and fees.
  • Only 1 in 3 teens know how to read a bank statement, Balance a checkbook, or pay bills.
  • Barely 1 in 5 teens know how to invest.

Judging by these numbers, the young people of our nation (“my” generation) have very little understanding of how to manage their finances.

This is a tragedy in my opinion, and many people don’t see a solution. I see it as an opportunity for credit unions to fill a void that perfectly fits our mission of people helping people and promoting thrift.

Financial literacy is often breezed over, if covered at all, during the average high school career. Though it is unfortunate, it is easy to see why. Teachers have so much to worry about teaching that financial literacy often doesn’t seem like a priority.

This is where Credit Unions come in. We have the ability, resources, and hopefully, passion to bring financial literacy to classrooms across our fields of membership. We are perfectly positioned to take advantage of resources like NEFE to help bring knowledge of financial management to students in our local area. NEFE_logo_4c

If you don’t already know what NEFE is, it is a non-profit organization dedicated to bringing people a financial literacy curriculum with a focus on high schools. They provide materials that are free to schools, including a full set of lesson plans, case studies, and workbooks. It is an incredible resource with a great track record of partnering with credit unions to bring it to local schools.

If your credit union hasn’t already looked into some kind of financial literacy program, now is the time to do it. The economy is struggling, debt is rising, and nearly a million people found themselves unable to stay afloat last year. The timing couldn’t be better for credit unions to jump in and help break the cycle caused by people living beyond their means. Many are finding themselves in a save-or-sink situation.

It is true that people just saving doesn’t benefit a credit union’s bottom line. In fact, if the dividends going out to deposit accounts aren’t matched by interest coming in from lending products, the profit margin can get tight.

Don’t think of promoting saving as an expense though, it is an investment in your community. When you teach somebody to save, it builds loyalty to your credit union. When they have some savings, they feel more comfortable, and are more able, to get lending products. Because they identify the credit union as the place that helped them to be financially sound, they are more likely to look at your credit union when shopping for a loan or credit card.

Show your community that you are looking out for them, teach them to be financially sound, and they will look to you more often when other decisions are at stake. Financial literacy is an investment in the future of your community. Though they may just be saving money now, they WILL be looking for that auto/home/personal loan in the future. If you can position your credit union as an advocate, it will be the place those people will look first.

Friday, May 9, 2008

My Audition for the 2008 Partnership Symposium

Sorry it took me so long to get this out there. It's been a crazy few weeks.

Friday, May 2, 2008

The Loop Out & About Episode 2

This Saturday, Maine State Credit Union hosted our Third Annual Walk to Stop Hunger in Maine. The past couple years we held it at the University of Maine in August. This year we moved it to Capitol Park, right in front of the capitol building here in Augusta.

Here’s some information from our Leagues site (the total number of Maine households differs slightly depending on the site you are looking at, such as The Good Shepherd Food Bank site)

More than 40% of Maine kids under the age of 12 show some evidence of hunger
19,375 Maine children are hungry
An additional 64,087 children are at risk of hunger
New data shows that 12% of Maine households, representing 161,000 people, experience food insecurity
Hunger and the risk of hunger are widespread among Maine's low-income families with children
The likelihood of experiencing hunger or the risk of hunger is directly related to income
Children living in households which experienced hunger or the risk of hunger are more likely to experience health or school-related problems.
Several groups are found to be at greater risk of hunger in Maine; children, adults in low income families, disabled persons, persons with special needs, the elderly, those living in rural regions and the inner cities of Maine's largest urban places.
Several factors contribute to hunger in Maine; including income growth that is outpaced by cost of living; high level of underemployment; widening gap between rich and poor; illiteracy; and lack of consumer information on nutrition.

The event has grown every year. The first year had 180 walkers, year two had 196, and this year we had a big jump up to 225. Thanks to all those who attended, donated, sponsored, and walked for this awesome cause.

Since the Campaign for Ending Hunger was started by the league in 1990, credit unions state-wide have raised over 2.7 million dollars for the cause. In 2007 the campaign raised over $360,000 to help those in need in our state. This year we matched last years walk by raising over $17,000.

This year we expanded the event to include a band, bounce house, balloon animals, and a fun run for those under 10. It really was a blast. We all had a great time hanging out after the walk, enjoying some dogs and burgers and listening to some great tunes provided by the band “Good Friday”, my personal favorite was their cover of “Waiting on the World to Change” by John Mayer.

This year First Lady Baldacci, who graduated with a degree in food and nutrition, joined us for the third year running to speak at the opening of the event and also walked the trail with our CEO, Normand Dubreuil. During her opening remarks she cited some of the above stats on hunger in our state, praised credit unions and Maine State CU for their involvement in ending hunger. My favorite quote from her was “This is something that certainly with the economy we have now is facing all of us, this issue, and is certainly something that we as Americans can end.”

Thanks again to everybody who showed up on Saturday to donate their money, canned goods, time, and services to help Credit Unions put a dent in the hunger problem in our state.

A special thanks goes out to Mike Stewart who raised the most money of an individual (over $700). He’s a great guy with a great attitude and an incredible dedication to the cause.

Also, thanks to Anthony Geroux, collections Manager here at MSCU, who led Team Geroux to raise the most of any team (over $2400).

We all had a blast! I hope anyone who didn’t make it this year will join us next year for this awesome community event for a lot of fun for a good cause.

Edited With: Windows Movie Maker

Filmed With: Cannon Powershot

Music: You Know That (Is Nothing New) - Bill Mallonee

Softball, Irony, and The Joy of Office Sports

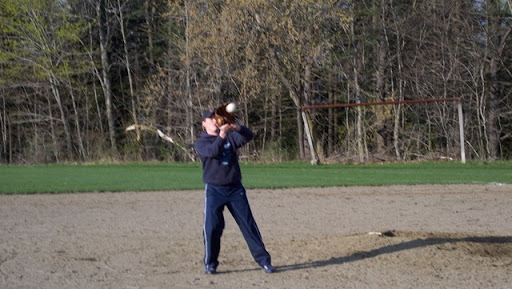
softball 002 On Saturday after our Walk to Stop Hunger (which I’ll have a post on later in the afternoon), a few of us got together for a good old fashioned game of wiffle ball home run derby.

After a few rounds, Shaun (a teller here at MSCU) was up to bat. Hans (who has spearheaded our softball team) was pitching. Hans tossed Shaun a pitch and was promptly hit in the throat by a powerful line drive off Shaun’s bat leaving a sizable red welt on his neck. We all joked that he’d better not do that with a softball at practice!

Fast-forward to last night. Maine State Credit Union’s softball team met for our first practice. We started with a quick game of catch just to warm up, and then set up on the field for a bit of batting practice.

Not a half hour into practice, Shaun was up to bat. We even joked that Hans was safe because he was playing left field, what could possibly go wrong? Paul (our security officer) threw the pitch and Shaun ripped one out to left field. Hans moved in to make the play. The ball caught the top of Hans’s glove and hit him right in the eye. Talk about ironic!softball 006

He ended up requiring a trip to the ER, 5 stitches, and sustained a small fracture on his cheekbone. Hans, being “The Man”, still showed up today for work, though he is sporting a Captain Hook eye patch and a pretty good shiner on his right eye.

Despite the minor hospitalization, we had a blast, got to know each other outside work, and got a bit of fresh air. I'm really looking forward to the start of the season next Thursday.

Moral of the story? You never know when lightning might just strike twice.

P.S. It was Hans who wanted me to post the picture :-P